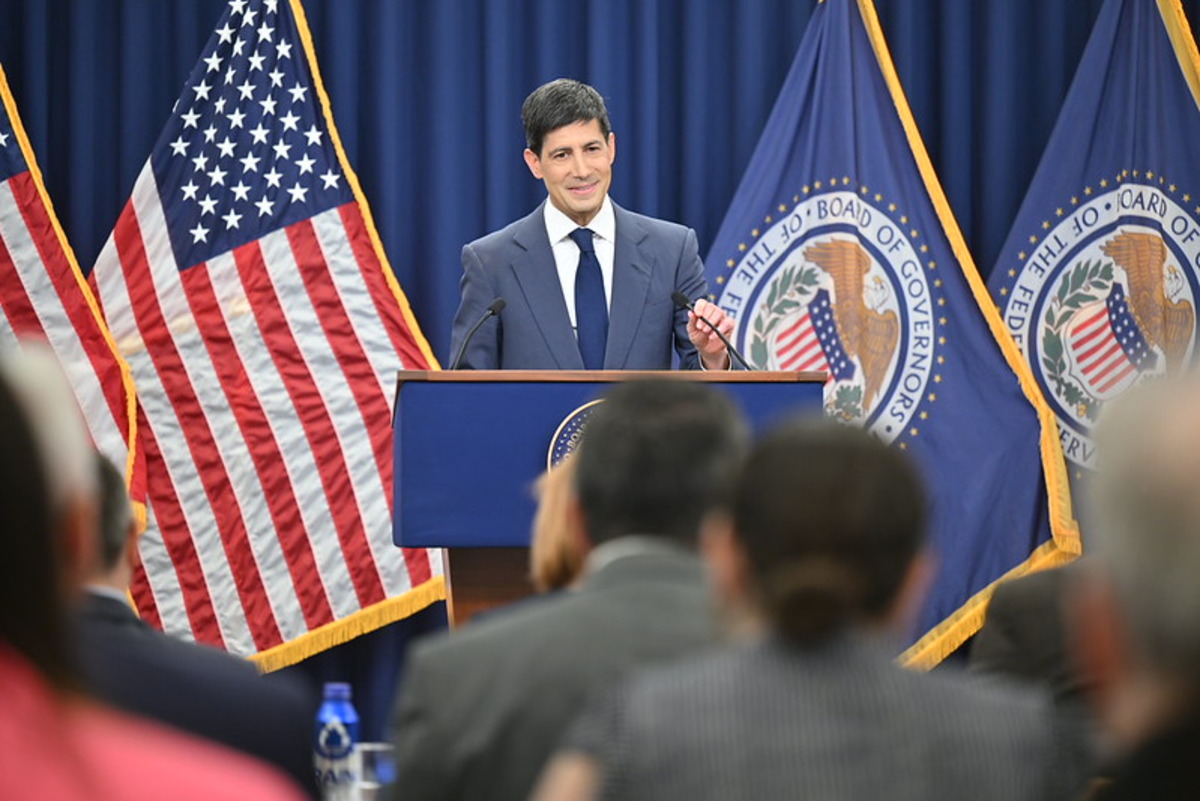
The U.S. economic picture is sending conflicting signals, leaving markets to weigh a hawkish Federal Reserve against evidence that both the labor market and consumers may be losing momentum. Federal Reserve Chair Kevin Warsh used his Jackson Hole speech Friday to make clear that inflation remains the Fed’s overriding concern, even as fresh labor-market revisions and the latest University of Michigan consumer survey point to growing economic strains.
Warsh Keeps Inflation at the Top of the Fed's Agenda
Warsh's message was particularly important for interest-rate-sensitive assets such as the Nasdaq 100. He said the economy appears to have strengthened, pointing to healthy consumer spending, rapid capital expenditure and resilient labor markets. He noted that unemployment remains at 4.1% and that jobless claims are near multi-decade lows.
But inflation, in his assessment, remains far too high: 12-month PCE inflation is running at 3.7%, while the six-month rate is 4.1%. Warsh said the Fed's predominant focus should therefore be on prices and that policymakers need to be confident that underlying inflation is moving toward 2% “clearly and at sufficient speed.”
LPL's Roach Sees a New Fed Communication Regime
LPL Financial Chief Economist Jeffrey Roach sees Warsh’s Jackson Hole speech as a distinctly hawkish shift in how the Fed communicates and makes policy. Warsh is pushing the Fed away from forward guidance and toward decisions based on real-time economic conditions, arguing that policymakers should not pre-commit to rate moves simply to satisfy market expectations.
Roach highlights Warsh’s warning that inflation remains too high, while strong capital spending, earnings growth and narrow credit spreads suggest monetary policy is not severely constraining the economy. At the same time, Warsh sees AI as a potentially transformative new factor of production that could lift productivity and the economy’s long-term growth potential, complicating traditional assumptions about inflation and labor markets.
The broader message, according to Roach, is that the Fed is entering a new monetary-policy era: less signaling, less market appeasement and greater reliance on timely data. That stance reduces the likelihood of the Fed providing markets with an easy roadmap for future rate cuts and helps explain the dollar’s strength following the speech, as investors interpreted Warsh as comfortable with keeping policy restrictive for longer.
Dollar Gains as Markets Absorb Hawkish Message
The immediate market reaction reflected the tension between Warsh's inflation focus and expectations for monetary easing. The dollar strengthened as traders reassessed the likelihood of near-term rate cuts, while Treasury yields became a critical gauge of whether the Fed's hawkish message would dominate the weaker-growth signals emerging from the economy.
For NQ, the reaction is especially important because elevated yields increase the discount rate applied to long-duration technology and growth stocks. A sustained rise in yields could therefore pressure Nasdaq futures even if economic data deteriorate, while a meaningful decline in yields could provide a valuation tailwind if investors begin to price a more pronounced slowdown and eventual Fed easing.
BLS Revision Raises Questions About Labor-Market Strength
That stance becomes more complicated when placed alongside Friday's preliminary BLS benchmark revision. The Bureau of Labor Statistics estimated that nonfarm employment for the 12 months through March 2026 was 79,000 lower than previously reported, while private employment was revised down by 178,000. The largest downward revisions included retail trade, wholesale trade, private education and health services, and professional and business services. The revision is not yet incorporated into the official employment data. The final adjustment will be made in February 2027 but it offers an early indication that the labor market may have been somewhat weaker than the monthly payroll data suggested.
For markets, that creates an important tension. The BLS revision argues for caution on the growth side, while Warsh is effectively arguing that inflation gives the Fed little reason to rush toward easier policy. That is a potentially uncomfortable combination for NQ. If weaker employment eventually translates into softer demand and lower inflation, falling Treasury yields could ultimately support technology stocks. But if labor-market weakness develops while inflation remains sticky, the Fed could find itself facing a stagflationary-style problem—less economic momentum without enough disinflation to justify aggressive easing.
Consumer Sentiment Adds Another Warning
The University of Michigan survey adds another layer to that picture. Final August consumer sentiment fell to 51.7 from 55.2 in July, leaving the index 11.2% below its level a year earlier. Both current conditions and consumer expectations deteriorated, while consumers also became more pessimistic about business conditions over both the one-year and five-year horizons. The survey found particular weakness among older, lower- and middle-income consumers and households without stock holdings.
Yet the consumer survey does not deliver an unambiguously dovish message for the Fed. One-year inflation expectations eased to 4.0% from 4.2% in July, but remain well above the 3.4% level recorded in February before the Iran conflict. Long-run inflation expectations held at 3.3%, also above their pre-pandemic range. Consumers are simultaneously becoming less confident about the economy and still expecting inflation to remain elevated.
Treasury Yields Become the Key NQ Transmission Channel
The other important takeaway from Warsh is that traders should not expect the Fed chair to provide the kind of explicit rate-path guidance markets have become accustomed to. Warsh said forward guidance should be limited and argued that markets should form their own expectations from economic information rather than looking primarily to the Fed for their next trade. He specifically highlighted Treasury prices, the dollar, credit conditions, commodities and broader market internals as signals the Fed itself will monitor.
That makes Treasury yields arguably the key transmission mechanism for NQ. If traders interpret the BLS and Michigan data as evidence of a sufficiently sharp slowdown, yields could fall and provide relief to technology valuations. But if Warsh's inflation message dominates and yields remain elevated, weaker economic data could actually become a negative for NQ rather than a bullish rate-cut signal.
NQ is showing a bearish divergence in trader positioning as futures dipped after a recovery post Warsh’s speech. MarketFramework data shows profitable traders are 51.8% long, compared with 58.1% long among unprofitable traders. That 6.3-percentage-point gap indicates that the traders currently making money are positioned more defensively than those on the losing side.
For NQ, the key takeaway is that the rally is not being confirmed by the traders with the stronger track record. If price pushes toward 29,790–29,800 and profitable traders continue adding to shorts rather than covering, that zone could become an important resistance area. Conversely, a sustained break above their average short entry would weaken the bearish positioning signal and could force short-covering.
The Trade: Weak Growth Is Not Enough
The market therefore faces a difficult equation: weaker jobs + weaker consumers would normally be bullish for rate-sensitive stocks, but only if inflation also cooperates. Warsh's message is that the third piece of that equation has not yet fallen into place.


