Wall Street snapped a four-day losing streak on Friday, though the rebound said more about oil than inflation. The Dow climbed 509.19 points, or 0.98%, to 52,573.29 ending its longest daily slide since late April while the S&P 500 added 0.86% to 7,656.98 and the Nasdaq Composite rose 0.96%.
The lift came as crude gave back part of a violent week: WTI fell 2.4% to $100.05 and Brent slid 2.8% to $104.61, cooling the energy-driven inflation scare that had pressured stocks all week. Even after the pullback, WTI still finished up nearly 10% on the week.
The Data Said Hike; Stocks Looked Away
August CPI landed in line on the headline, up 0.4% on the month and 3.4% on the year but core prices rose a firmer-than-expected 0.3%, keeping the inflation problem alive.
Traders looked past it; the bond market did not. The 2-year Treasury yield topped 4.6%, its highest since July 2024, and CME FedWatch now prices roughly an 86% chance of a quarter-point Fed hike next week. “The debate has quickly shifted from whether the Fed will hike to … how many hikes this cycle will ultimately require,” said Principal Asset Management’s Seema Shah, who does not expect a one-and-done.
That is the day’s real tension: equities rallied on oil relief while rates priced a harder Fed.
Dollar Round-Trips, NQ Holds its Break
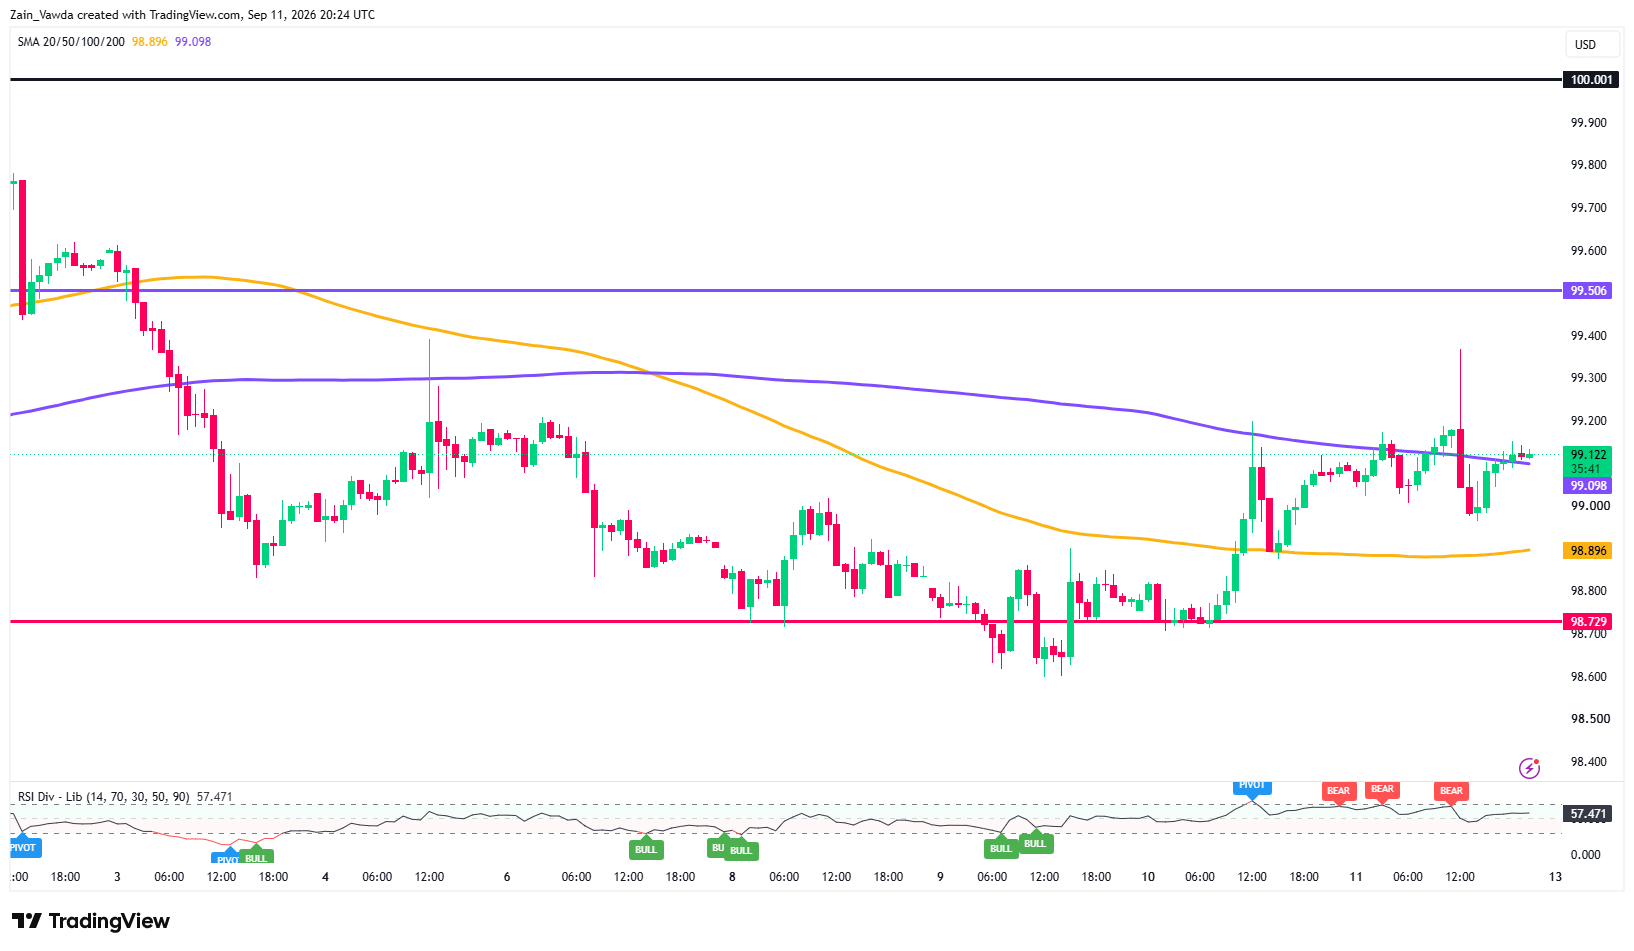
The dollar told the same split story. The DXY spiked to about 99.36 (intraday high) on the CPI before fading to roughly 99.04 as longer-dated yields eased, a classic curve flattener, the front end pricing the hike while the long end signals it may contain inflation.
US Dollar Index One-Hour Chart, September 11, 2026
Source: TradingView
In futures, the Nasdaq 100 held the break of the week’s descending trendline it made after the print, using the 29,265–29,291 shelf as its pivot. None of it is an all-clear: it is a relief bounce inside a down week, delivered the business day before a live Fed decision.
The Week Ahead: A Central-Bank Triple-Header
Everything routes through Wednesday. The FOMC decision (2:00 p.m. ET, Sept 16) is the marquee event, with a hike now close to fully priced, so the market’s focus shifts to whether this is insurance or the first of several.
The statement’s tone, the dissent count and Federal Reserve Chair Kevin Warsh’s press conference, more than any accompanying projection, will move the tape.
The same morning brings August retail sales, a rebound-tipped read on the consumer. Then the world crowds in: the Bank of England decides Thursday and the Bank of Japan on Friday, where a hawkish shift would jolt USD/JPY.
Friday is also quad witching, which typically lifts volume and volatility as September contracts expire.
The standing wildcard is energy. Saudi Arabia shut its East-West crude pipeline as a precaution after attacks this week, a fresh supply risk that, like Iran and Hormuz, feeds straight back into the Fed’s inflation math.
Key Events & Dates
| Day | Key Events | Why It Matters |
|---|---|---|
| Tuesday 15 | Empire State mfg; UK jobs; FOMC begins | Secondary US data ahead of the decision |
| Wednesday 16 | Retail sales; UK CPI; FOMC + Warsh presser | The main event, hike ~86% priced |
| Thursday 17 | BoE decision; jobless claims; Philly Fed | Global rate leg; UK policy divergence |
| Friday 18 | BoJ decision; Japan CPI; quad witching | USD/JPY risk + expiry-driven volatility |