NQ chops near its 20/50-day MAs as Alphabet reports alone Wednesday; Tesla, IBM and Texas Instruments follow, with rising oil-driven Treasury yields adding a valuation headwind into the print.
The Nasdaq 100 futures (NQ) are chopping around their 20- and 50-day moving averages for a third straight week, closing at 29,316 on Tuesday, after failing to hold a brief reclaim of the average earlier this week. With price pinned near this key technical zone and the broader uptrend still intact above the 100- and 200-day averages, traders are looking to earnings from Alphabet Wednesday after the bell to force a resolution one way or the other, as the artificial intelligence (AI)-infrastructure rally that has powered tech futures since April faces its first real test of the summer.
Multiple Forces in Work
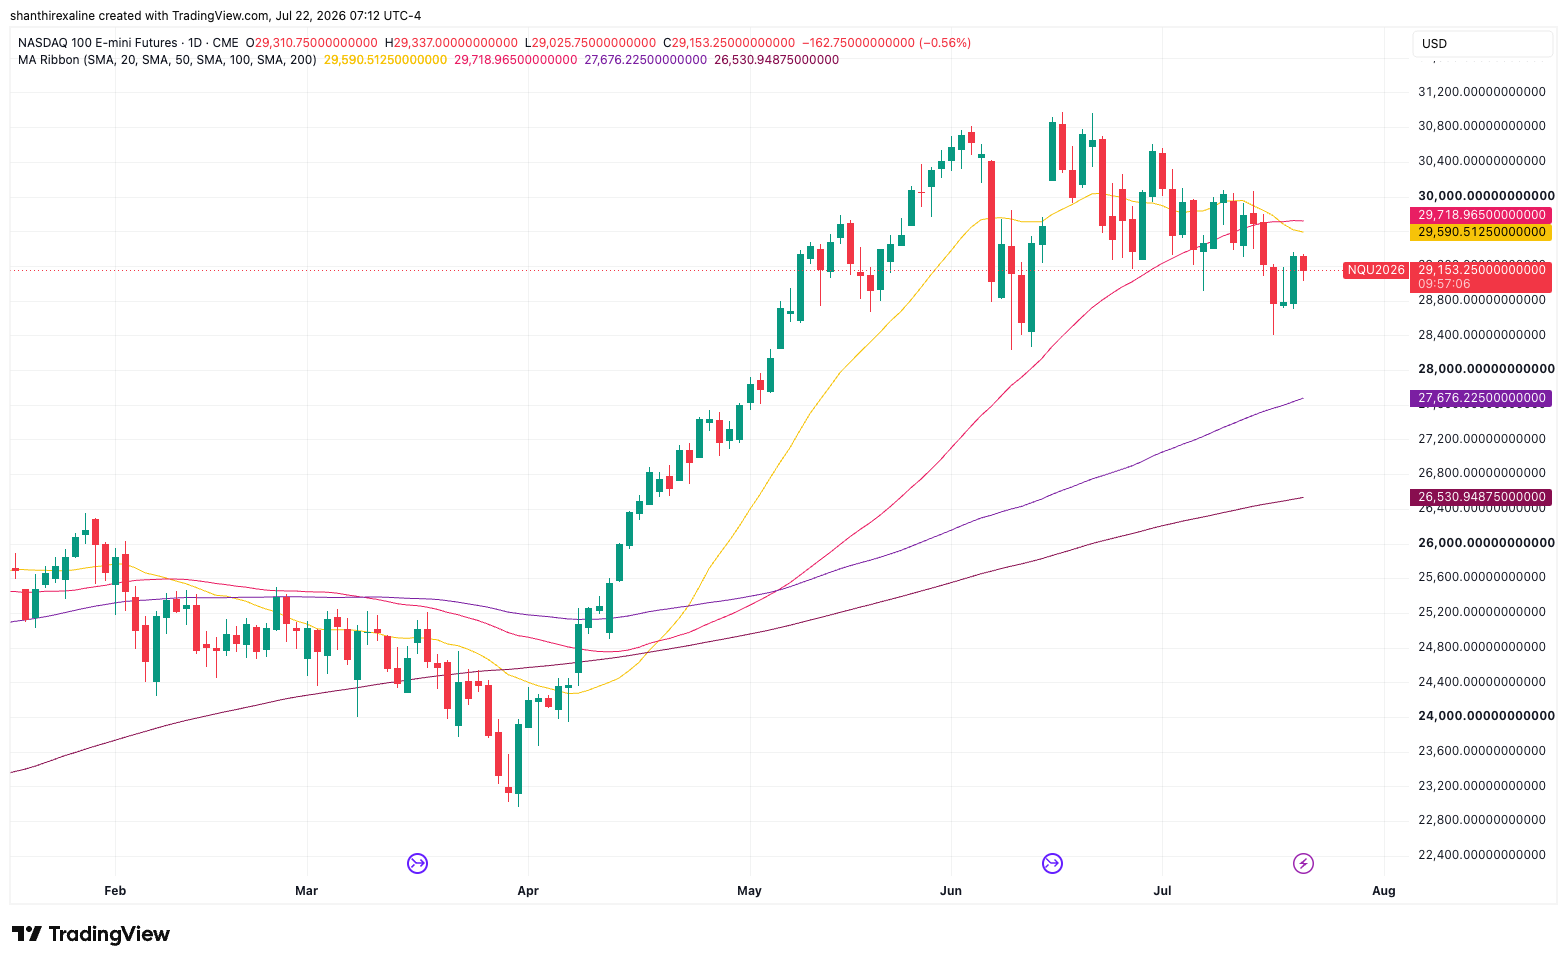
The setup into the print is a tug-of-war between two forces. On one side, the technical structure argues for caution: NQ is trading both its 20-day (29,589.55) and 50-day (29,718.54) simple moving averages on Wednesday, with the 20-day itself beginning to flatten, which is a sign the recent bounce off the July 17 low near 28,408.25 has lost momentum rather than confirmed a new leg higher.
On the other side, the fundamental backdrop into earnings remains constructive: Alphabet is expected to report Google Cloud growth near 60% and has guided 2026 capex to $180–190 billion, spending that has directly fueled the AI-infrastructure trade underpinning this year's rally in chipmakers and hyperscalers alike.
Complicating the picture further, a sharp move higher in the 10-year Treasury yield pushed by this week's spike in crude oil prices tied to the Iran conflict. This has added a valuation headwind for growth stocks just as earnings season hits its highest-stakes stretch, leaving NQ's next directional move likely to hinge less on chart levels and more on how the market reconciles rate pressure against another quarter of heavy AI spend.
Chart Structure: A Market Stuck at the Ribbon
The daily chart tells a story of indecision rather than trend continuation. After topping near 31,000 in mid-June, the NQ corrected sharply into late June, attempted a recovery back toward roughly 30,600 by the end of June, then rolled over again — breaking below the 20/50-day MA ribbon by early-July. A sharp bounce followed, briefly pushing price back above both averages, only for the reclaim to be rejected. The result is a market that has crossed the moving-average ribbon multiple times in three weeks without establishing clear control in either direction. Longer-term trend health isn't in question — the 100-day (27,676) and 200-day (26,531) averages remain well below price. The near-term tape is unmistakably rangebound.
Source: TradingView
Retail positioning data tells a nuanced story: 54% of profitable traders are currently holding long positions in NQ, and notably, a similar 53.7% of unprofitable traders are also long, according to MarketFramework's Positioning Edge tool. The near-total overlap suggests being long hasn't been the differentiator between winning and losing trades lately, with execution, sizing, or timing important more than direction here, leaving Wednesday's earnings as the probable tiebreaker.
Wednesday's Catalyst: Alphabet Goes First, Alone
Alphabet’s reports due after the close gives the market its first same-day read on cloud growth and AI capex commentary for the quarter — with Microsoft's Azure numbers not landing until next week, meaning Wednesday’s reaction won't have an immediate cross-check from its closest cloud peer. That raises the stakes on how the market interprets Alphabet in isolation.
Investors will be watching Google Cloud's growth trajectory and whether enterprise AI demand can sustain recent pace, alongside scrutiny of Alphabet's aggressive capex guidance and what it signals for margins. A notable wrinkle this quarter: Alphabet's minority stake in Anthropic has been marked up sharply enough that headline EPS could significantly overshoot consensus on paper gains alone, meaning traders will need to look past the top-line number to gauge the market's real reaction to core Search, Cloud, and advertising performance.
Apart from Alphabet, IBM, Texas Instruments and Tesla are all scheduled to report after the close. Of these, Tesla's report carries its own weight for the index. The delivery numbers are already public — a record 480,126 vehicles for the quarter, up 25% year-over-year and well above the roughly 406,000 consensus estimate — but the stock has still drifted lower into the print, trading below its 50- and 100-day averages, because the real debate isn't about volume.
Analysts are focused on automotive gross margins under aggressive promotional pricing, the cost drag from Tesla's AI and Cybercab investment, and whether profitability can catch up to delivery growth; EPS estimates span a wide range as a result. Options markets are pricing roughly a 7% post-earnings move. IBM and Texas Instruments round out the after-hours slate but carry comparatively less index-moving weight, making Alphabet and Tesla the two prints most likely to set tone for NQ's Thursday open.
The Rates Overhang
Equity futures aren't trading in a vacuum. A renewed spike in crude oil, driven by escalating U.S.-Iran tensions, has pushed the 10-year Treasury yield to a two-month high this week. Rising yields tend to compress the valuation multiples assigned to high-growth tech names, meaning even a solid earnings beat may face resistance if bond yields keep climbing in tandem with oil. This cross-asset dynamic of oil driving rates, rates pressuring tech multiples is arguably as important to NQ's next move as the earnings prints themselves.
NQ Futures Into & Through Alphabet Earnings
| Scenarios | NQ Levels | Follow-through catalysts |
|---|---|---|
| Double beat; Cloud growth- 60%+; ad revenue beat; capex guidance seen as justified | Reclaim and hold 20/50-MA, next upside targets: 29,865, 30,000 and 30,400 | 10-year yield; semiconductor follow-through as AI capex worries abate |
| In-line results; no major surprise on Cloud growth or capex | Range bound between 28,950-29,590 | Rates and oil-driven macro flows dominate instead; wait for Microsoft (July 29) as next real catalyst |
| Cloud growth decelerates; revenue undershoots estimate; Capex guidance revised | Break and hold below 28,950 (VWAP support); next target 28,707, then 28,550 (July low) | Watch for spillover into broader AI-infrastructure names (chips, hyperscalers); risk of triggering a deeper unwind toward 100-day MA (~27,676) |
What to Watch Into the Close
- 29,590–29,720 — the 20/50-day MA zone NQ needs to reclaim and hold to signal the consolidation is resolving bullishly
- 28,410 — the July low; a breach here would confirm the bounce has fully failed
- 10-year Treasury yield: continued climb would pressure tech valuations regardless of earnings quality
- Alphabet’s commentary — the clearest read on whether AI infrastructure demand still justifies current capex levels
With price sitting squarely at a level it has fought over for weeks, tonight's earnings are positioned to be the deciding vote — not just for two mega-cap stocks, but for the near-term direction of the broader AI trade.


