Nasdaq (NQ) ended Wednesday higher, but it was the clear laggard on a green day for U.S. stocks and the split beneath the surface explains why.
A relief rally in bonds lifted the parts of the market that benefit from lower rates, while the technology and AI names that dominate the Nasdaq were held back by a fresh wobble in the AI trade.
A Green Day, But Tech Brought Up The Rear
The headline moves were modest and skewed away from tech. The Dow added about 113 points (0.2%) and the S&P 500 rose 0.3%, but the Nasdaq Composite managed just 0.1%. The spark was the bond market: after the
Treasury said it would at least double its buybacks of longer-dated debt, the 30-year yield fell more than 7 basis points to 5.206%, down from the 19-year high above 5.33% it touched a day earlier and the 10-year eased to 4.658%.
Lower yields pushed money into rate-sensitive and value names. Lowe’s rose more than 2%, Home Depot more than 1%, and McDonald’s close to 1%. Merck jumped more than 11%, helping power the Dow after its vaccine partner Moderna more than doubled on strong late-stage cancer-trial data.
As Procyon’s Massimo Santicchia framed it, the strength in value stocks signals the economy and earnings cycle are still healthy, even as the market now carries a “tension” between solid fundamentals and a higher cost of capital.
Why the Nasdaq Couldn’t Keep Up
The index’s problem was concentration in exactly the names under pressure.
The Wall Street Journal reported that OpenAI’s second-quarter results underwhelmed, revenue grew 18% from the prior quarter, but losses widened, and the growth looked tepid next to rival Anthropic. That reignited nerves about whether the AI spending boom is paying off, and the chipmakers wore it: Broadcom and AMD each fell around 4%.
Marvell was the exception, jumping 8% on a tensor-processing-unit agreement with Google that also handed Alphabet a warrant to buy up to $12.2 billion of Marvell stock but one winner couldn’t offset the broader AI-hardware wobble.
The cross-current that matters for the Nasdaq: Wednesday’s Treasury move capped the long end of the curve, but the July Fed minutes, released the same afternoon, leaned hawkish. Officials signaled rates may still need to rise if inflation doesn’t cool, and three of them had already voted to hike in July.
For the high-multiple, rate-sensitive stocks that dominate the Nasdaq, that is the uncomfortable pairing, falling long-end yields on one side, a Fed still openly weighing a hike on the other.
Nasdaq (NQ) Four-Hour Technical Outlook
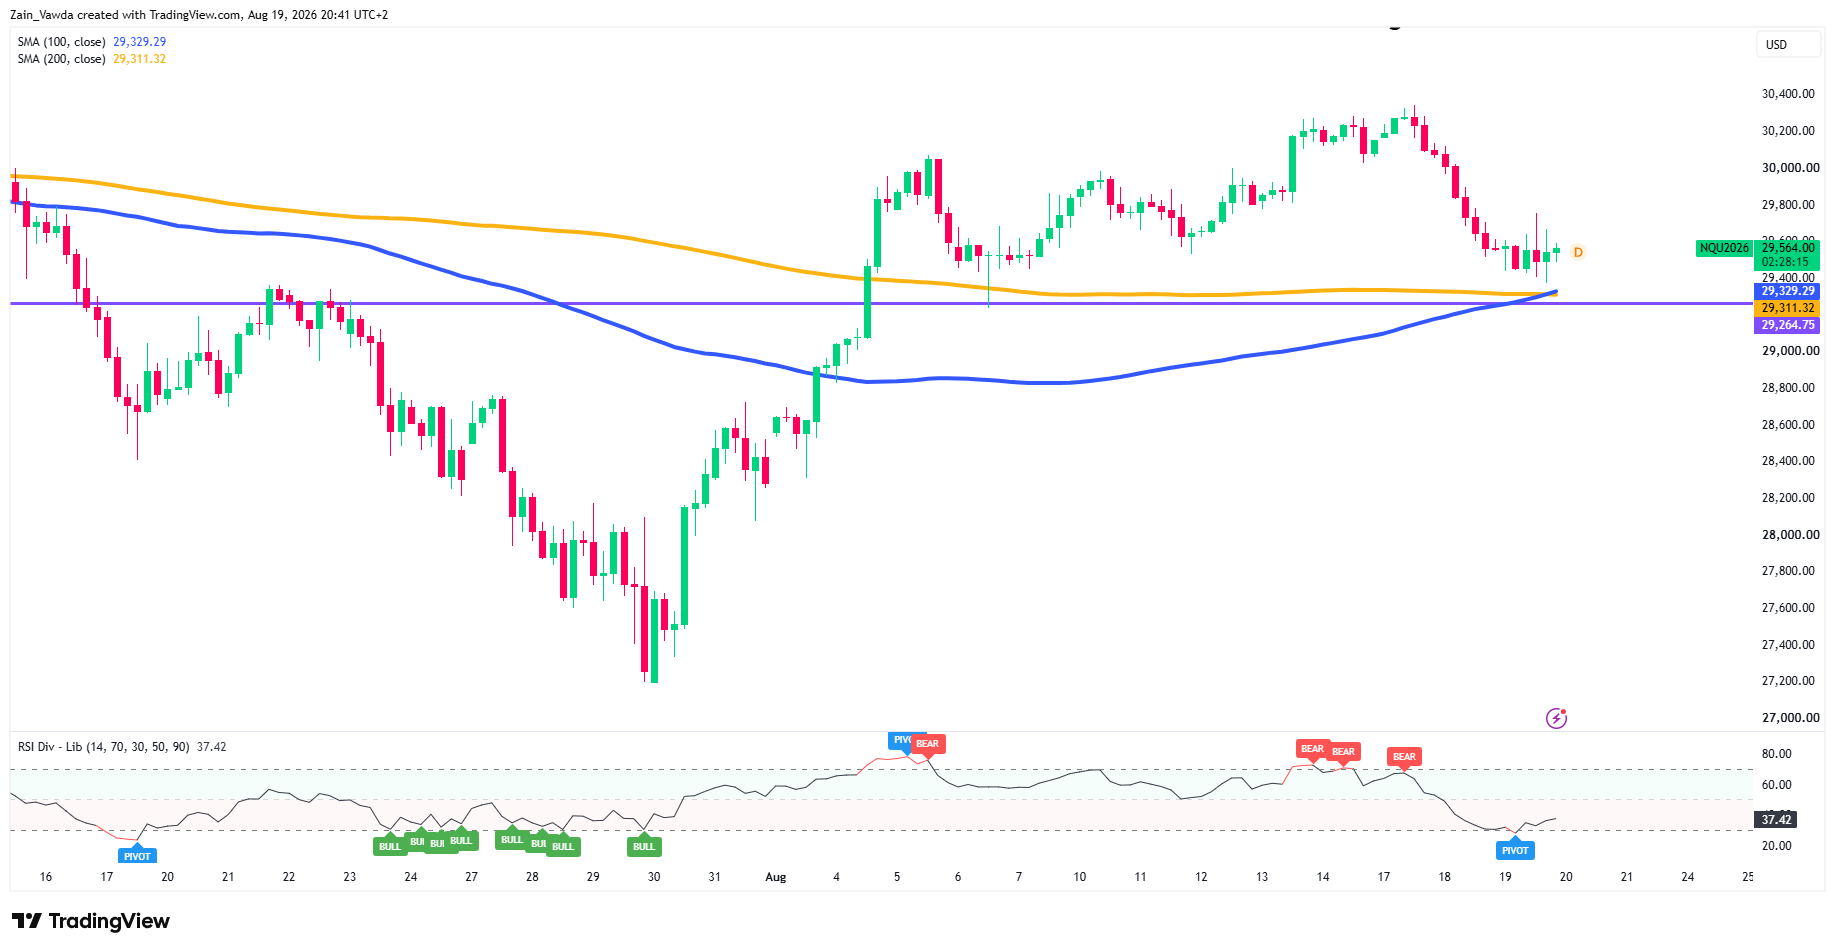
On the four-hour chart, NQ trades near 29,564 after pulling back from the August 17 high around 30,400. The decline stalled at a tight confluence shelf where the 100- and 200-period moving averages (29,329 and 29,311) sit just above the 29,264.75 pivot that buyers defended repeatedly in June.
Nasdaq H4 Chart, August 19, 2026
Source: TradingView
Price is holding above that band and turning up, with RSI recovering from a washed-out 37.42 off a fresh momentum low, the bearish divergence that flagged the mid-week top has now played out.
That makes 29,265–29,329 the line that matters: hold it and the pullback stays a dip, with 29,800 the first reclaim toward 30,000 and 30,400. A four-hour close below 29,264.75 opens 29,000, then the 28,800 breakout retest.
The Outlook for the Rest of the Week
The back half of the week is light on data but heavy on tone. Thursday brings Walmart’s earnings before the open, the definitive read on the U.S. consumer after last week’s soft retail sales alongside weekly jobless claims and the Philadelphia Fed manufacturing index.
Friday delivers the flash August PMIs for manufacturing and services, where the consensus looks for a modest cooling.
For the Nasdaq specifically, though, this is really a holding week. The catalysts that decide its next big move sit in the following week: Nvidia’s earnings on August 26, the single biggest test of the AI-spending thesis and the Jackson Hole symposium on August 27–29, where new Federal Reserve Chair Kevin Warsh delivers his first keynote.
Until those come into view, expect NQ to trade around its technical shelf and the day’s headlines.
Scenario Matrix. The Shelf Into This Week’s Catalysts
| Scenario | Trigger | NQ Implications |
|---|---|---|
| Bull | Shelf 29,265–29,329 holds; WMT/PMIs steady; yields contained | Reclaim 29,800 → 30,000 → retest 30,400 |
| Base | Chop above the shelf; mixed data; AI caution lingers | Range 29,300–29,800 drift into Nvidia (Aug 26) |
| Bear | 4h close below 29,264.75; hot data lifts yields or AI weakness broadens | 29,000 → 28,800 breakout retest |
Key Considerations
Profitable traders are likely to trade the shelf with defined risk, going long only on a hold or reclaim of the 29,265–29,329 band, stop below the pivot rather than chasing an intraday bounce into 29,800 resistance before it is earned.
In a week caught between falling yields and a hawkish Fed, the edge is letting the shelf resolve before committing size.
Keep a close watch on retail trader positioning using Positioning Edge on MarketFramework for more insights.


