It is a grim Tuesday for most of Wall Street but not for chipmakers. At midday the Dow was down more than 600 points, about 1.1%, and the S&P 500 had slipped around 0.4%, dragged lower by climbing oil prices, sticky inflation worries and a fresh US–Canada trade war.
Yet the tech-heavy Nasdaq was clinging to the flatline and even edging green. The reason is simple: two chip stocks are on fire. Qualcomm has jumped about 10% and Intel is up around 5%, and between them they are almost single-handedly holding the market together.
S&P 500 Heatmap
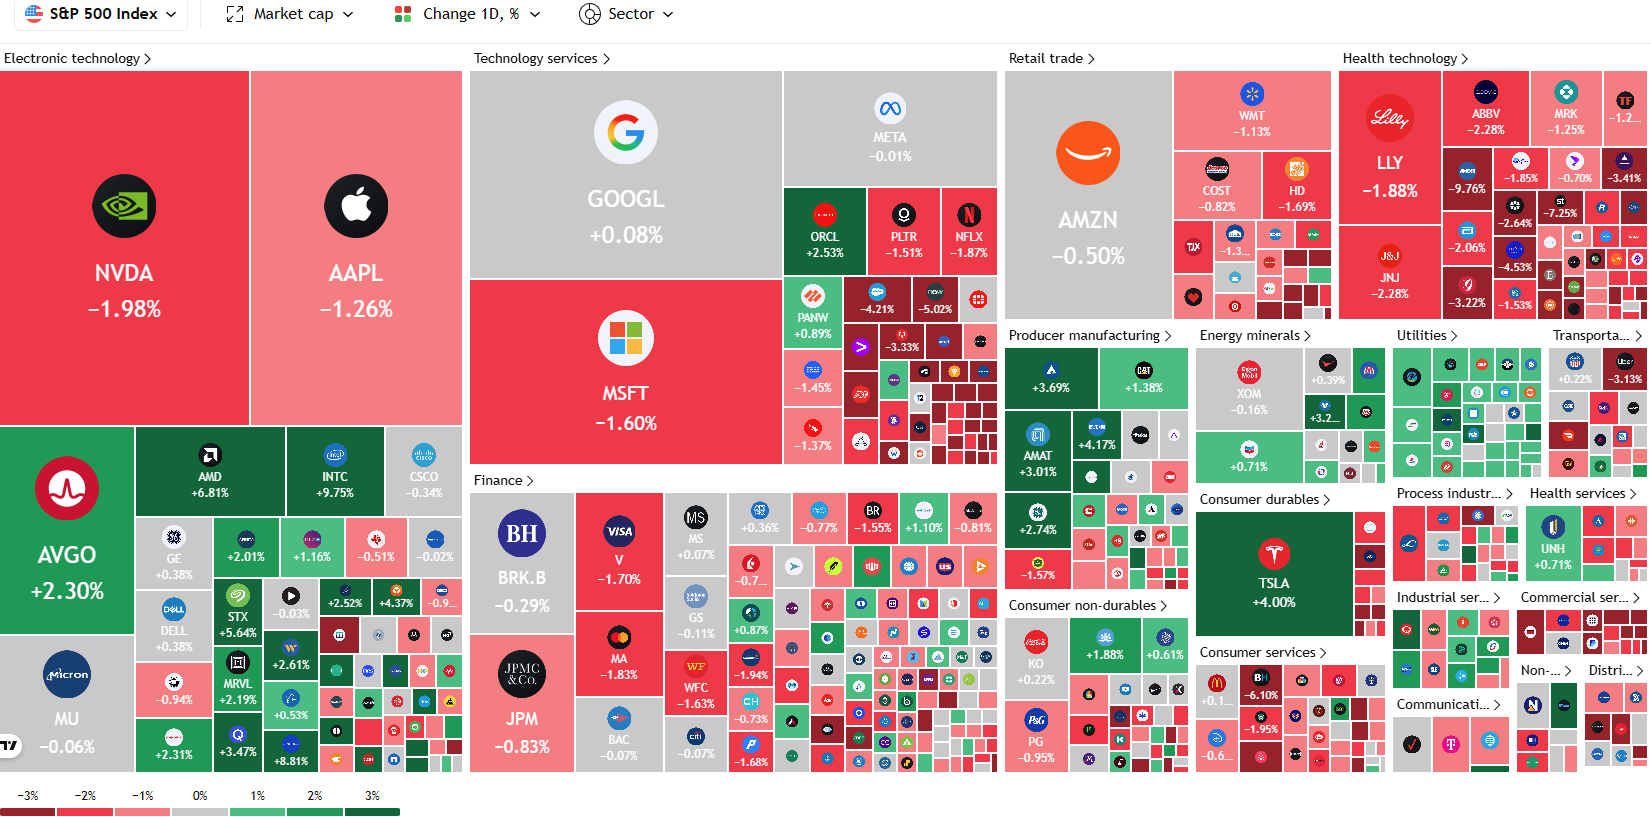
Source: TradingView
Qualcomm’s Big Amazon Win
Qualcomm’s surge, its biggest one-day jump in years came after it announced a partnership with Amazon Web Services (AWS), Amazon’s cloud arm.
The two will work together across several generations of custom chips to power AWS’s AI data centres, focused on “inference”, the everyday job of running AI models to answer questions, as opposed to the heavy work of first training them.
Amazon is now Qualcomm’s second big cloud customer after Meta, and as a sweetener Amazon received a warrant (a right to buy shares later) for up to 25 million Qualcomm shares.
In plain terms, a company long seen as just a smartphone chipmaker suddenly has a credible seat at the data-centre table, the arena Nvidia dominates. The deal pushed Qualcomm back into positive territory for 2026 after months of lagging its peers.
Intel Gets a Musk-Sized Vote of Confidence
Intel’s move came from a broker upgrade with a big name attached.
Northland Capital Markets’ Gus Richard lifted Intel to “outperform” (his version of a buy) with a $120 price target, roughly 25% above Friday’s close. His reasons: a shortage of server processors, and Intel’s role in “Terafab”, the giant Texas chip factory being built by Elon Musk’s Tesla and SpaceX.
Intel is the lead manufacturing partner, making the chips on its most advanced process. The first phase alone is worth $16.8 billion, with the total potentially reaching $119 billion and Richard argues a customer that size validates Intel’s struggling contract-manufacturing (or “foundry”) business at exactly the right moment.
TODAY’S TWO BIG MOVERS
| Stock | Catalyst | Move Today | Why It Matters |
|---|---|---|---|
| Qualcomm (QCOM) | Multi-generation deal to build custom AI-inference chips for Amazon’s AWS; Amazon gets a warrant for up to 25M shares | ≈ +10% | A real foothold in data-centre chips. Nvidia’s turf; second hyperscaler customer after Meta |
| Intel (INTC) | Northland upgrade to “outperform”, $120 target; cites a server-chip shortage and Intel’s foundry role in Musk’s $16.8bn+ “Terafab” | ≈ +5–7% | Big-name validation for Intel’s troubled contract-manufacturing business |
What This Means for Markets
Strip away the noise and both moves point the same way: the money pouring into AI infrastructure keeps creating new winners, and right now that is where market leadership is bunched up. It is why, even on a red day, the most-searched and most-traded names are almost all chipmakers, Nvidia, Micron, Sandisk, AMD and South Korea’s SK hynix alongside Qualcomm and Intel as an ongoing memory shortage and enormous cloud spending keep pulling cash into the sector.
But narrow leadership cuts both ways. With energy stocks at record highs and the Dow sinking on oil and trade-war fears, the broad market is leaning on a handful of chip names to stay afloat, if those wobble, there is little else holding things up. And the next tests come fast: Friday’s US inflation report and the Federal Reserve’s rate decision next week, where a hike is still on the table.
A New York Fed survey out today offered mild comfort, the public’s inflation expectations held steady in August even as worries about the job market ticked up.
For now, chips are doing the heavy lifting. The real question is how long they can carry the whole load.