The Template Was Set Last Night
Wednesday’s earning prints drew the map for how this season trades.
Microsoft beat and rose ~3% (extending those gains to 11% in pre-market trade on Thursday). The main catalyst being Azure accelerating to 43% and the capex envelope held;
Meta grew revenue 28% and still fell ~10% because profit dropped 14% and the spending floor ticked higher.
Same AI boom, two very different bills.
Apple and Amazon close the week after today’s bell — and they sit at opposite ends of exactly that spectrum.
Apple — The Anti-Capex Megacap
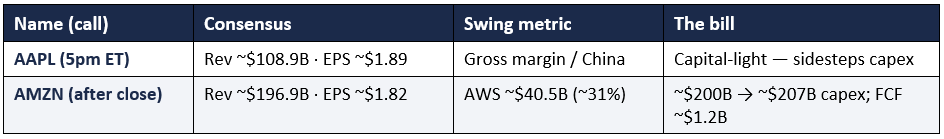
Apple (call 5pm ET) is the print that sidesteps the capex debate.
Consensus sits near $108.9B revenue and $1.89 EPS (~20% YoY), with iPhone around $53–55B and Services a record ~$31.4B at 70%-plus gross margin.
The stock brushed a $5-trillion valuation and an all-time high this week — the best-performing Mag 7 name of 2026 — precisely because its capital-light, on-device AI strategy avoids hyperscaler-scale spending. So the risk here isn’t the bill; it’s the gross-margin guide and China. An AI-driven memory-chip shortage is already pushing hardware prices up, China is strong (iPhone shipments +24% YoY) but fiercely contested, and this is Tim Cook’s final call before John Ternus takes over.
A cautious margin or China tone is the vulnerability — not capex.
Amazon — The Purest Capex Referendum
Amazon is the other side of the trade.
Consensus: $196.9B revenue, $1.82 EPS, AWS ~$40.5B (~31%). AWS has accelerated three straight quarters (20% → 24% → 28%), and banks have lifted estimates toward 33% on Anthropic and OpenAI demand flowing through Bedrock — a fourth straight acceleration would be the bull confirmation. But the bill is heavy: 2026 capex guided at $200B with consensus already crept to ~$207B, and trailing free cash flow has collapsed to roughly $1.2B.
If CEO Andy Jassy raises the capex guide — widely expected — without AWS clearing a high bar, Amazon risks the Meta treatment. Options imply a ~6–7% move.
Apple and Amazon Prints at a Glance
Source: Created by Zain Vawda Using Canva
What it Means for the Nasdaq
The read-through to the NQ is direct: the big-four hyperscalers make up more than 18% of the Nasdaq-100, and tonight closes a megacap gauntlet that has already delivered one relief and one rout.
Apple’s sheer index weight makes it the single largest overnight swing factor — a clean print steadies the tape — while Amazon’s capex verdict decides whether the “spend is finally being punished” narrative hardens into Friday.
Base case: the divergence continues — reward the bill that’s contained, punish the one that isn’t. AWS growth and Apple’s margin guide are the two numbers that move the NQ overnight.
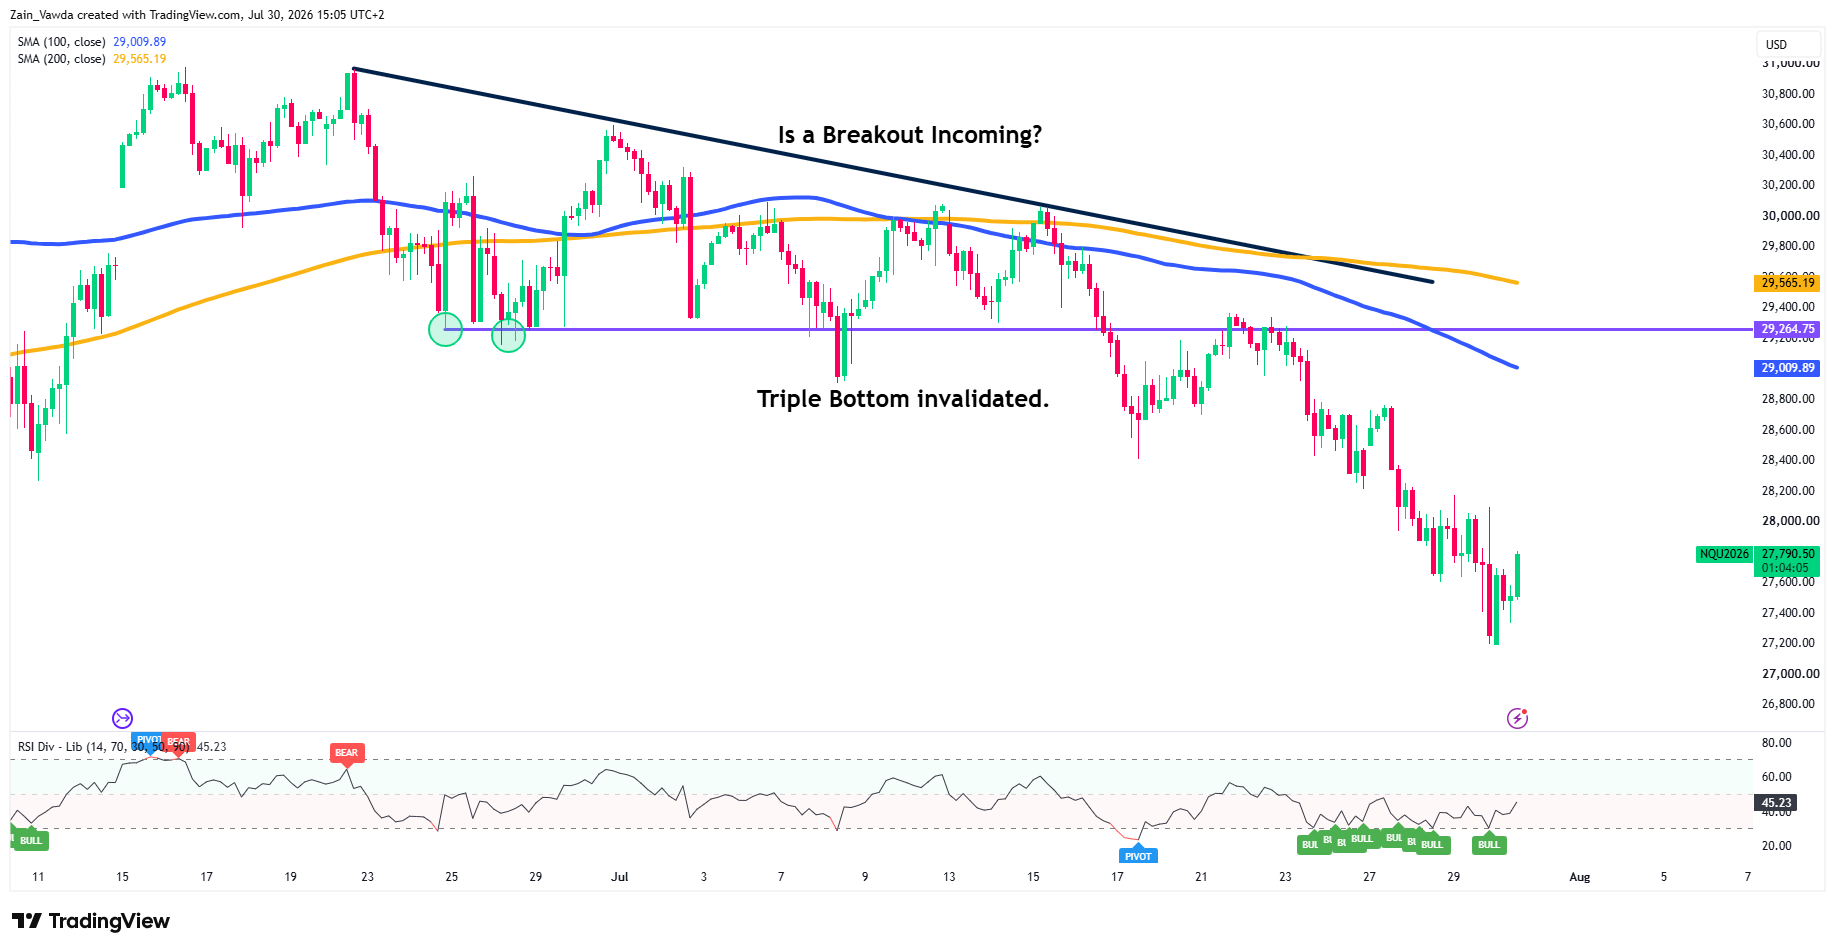
Nasdaq 100 (NQ) Four-Hour Chart, July 30, 2026
Source: TradingView
Looking at the charts and the H4 timeframe is firmly bearish.
Price at ~27,790 sits far below the 100- and 200-MAs (29,010 / 29,565), which now cap rallies.
The slide from 30,000 bottomed near 27,200 and price is staging a relief bounce, RSI recovered to ~45 but still sub-50 — momentum stabilising, not turning.
Treat it as a countertrend pop within a downtrend: 28,000 is first resistance, then the 29,264 shelf.
Support is 27,200; losing it opens 27,000.
The bounce looks fragile into tonight's Apple and Amazon prints.
Retail Trader Sentiment
Looking at data from the MarketFramework Positioning Edge Tool and it is showing a "Strong Bullish Divergence," which is driven by the positioning gap between different trader cohorts.
Currently, profitable traders are leaning bullish with a 57% long exposure. In contrast, unprofitable traders are completely neutral, holding a 50% long position. This creates the headline metric: profitable traders are exactly 7% more long than unprofitable ones.
If you believe in tracking the smart money this might provide a strategic edge. Because profitable traders are actively accumulating long positions (57%) despite the asset being down 1.49% on the day, they are likely anticipating a price reversal or bounce.


