U.S. business activity accelerated to a three-month high in April after nearly contracting in March, according to the results of S&P Global’s purchasing managers’ survey released Thursday. The positive development, however, is far from offering a relief, as the U.S.-Iran war continued to push up prices and disrupted supplier deliveries.
Crunching the Numbers: Manufacturing as well as services activity expanded at a slightly faster pace in April, although the pace of expansion remained subdued.
- Manufacturing PMI: 54 Vs. 52.3 in March (consensus 52.5)
- Services Business Activity PMI: 51.3 Vs. 49.8 in March (consensus 50.5)
- Composite Output PMI: 52 Vs. 50.3 in March
The manufacturing output index climbed to a nearly four-year high to 55.7, with the growth partly due to stock building amid concerns over supply availability and price hikes.
Input cost inflation accelerated, and supply delays worsened at a pace not seen since mid-2022, causing the largest monthly jump in average selling prices for goods and services since July 2022.
“A rebound in business output growth in April is good news after the near-stagnation seen in March, but over the past three months we have seen the weakest expansion of output recorded since the start of 2024 with the war in the Middle East squarely to blame,” said Chris Williamson, Chief Business Economist at S&P Global Market Intelligence.
Growth Running Below-Trend? Williamson said, “The April PMI is broadly consistent with the economy struggling to manage annualized growth in excess of 1%, with the vast service sector acting as the principal drag.”
Composite PMI Vs. GDP
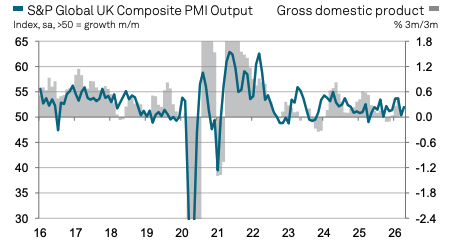
Source: S&P Global
Order growth stalled for a range of services such as travel & tourism and financial products as as the war caused hesitancy in spending among both household and
business customers. Surging prices and the prospect of higher borrowing costs acted as additional deterrents.
Read Next: Jobless Claims Tick Up, Slightly Above Consensus, as Traders Look Ahead to Next Week’s Fed Decision