The U.S. dollar is making its move — and it's dragging everything else with it.
The U.S. Dollar Index (DXY) pushed to 101.7 on Wednesday, its highest level since April 2025, extending a four-session winning streak as markets absorb the full implications of the Federal Reserve's June 17 meeting.
This isn't a safe-haven spike. It's a structural repricing — and for futures traders, understanding what's driving DXY here is the key to positioning across oil, gold, equities, and rate-sensitive crosses for the rest of Q3.
The Fed Pulled the Trigger
Federal Reserve under Chair Kevin Warsh held the fed funds rate at 3.50%–3.75% on June 17, but the accompanying dot plot delivered a hawkish shock, projecting a 25-basis-point hike in 2026 versus quarter-point cuts in the previous two projections.
Year-end PCE inflation was revised up 0.9 points to 3.6%, and May CPI had already landed at 4.2%, the hottest reading since April 2023.
The market reaction has been swift. According to CME FedWatch, traders are now pricing a 68% probability of a September hike, up from just 29% a week ago. That repricing is the engine behind DXY's move, and it isn't done.
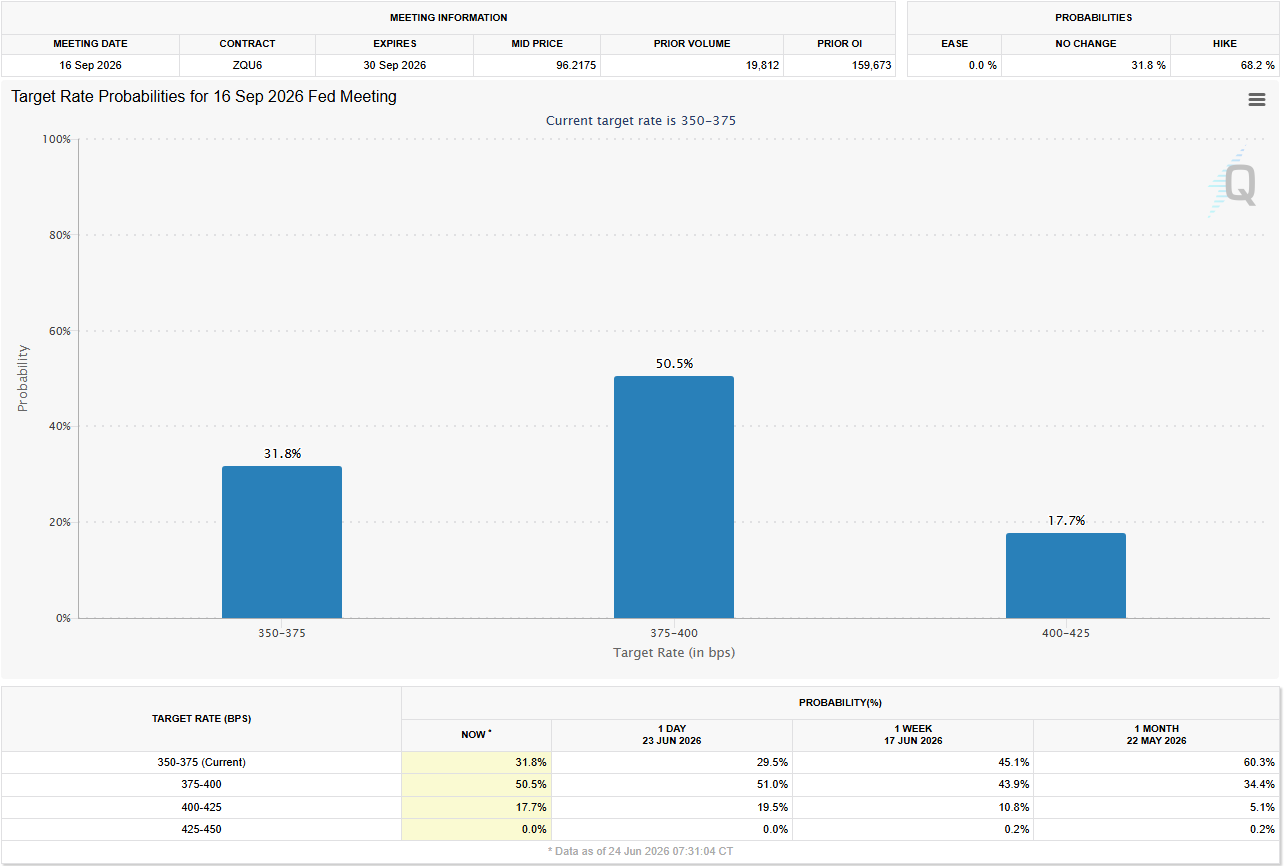
Source: CME FedWatch Tool
The Transmission Is Everywhere, Oil, Gold and Equities
For oil (CL1!) traders, a stronger dollar is a persistent structural headwind on top of already-collapsing oil prices. Oil has shed around 22%+ in a month as Iran peace talks advance. Watch the $70 handle as the next psychological test.
Oil Futures (CL1!) Four-Hour Chart, June 24, 2026
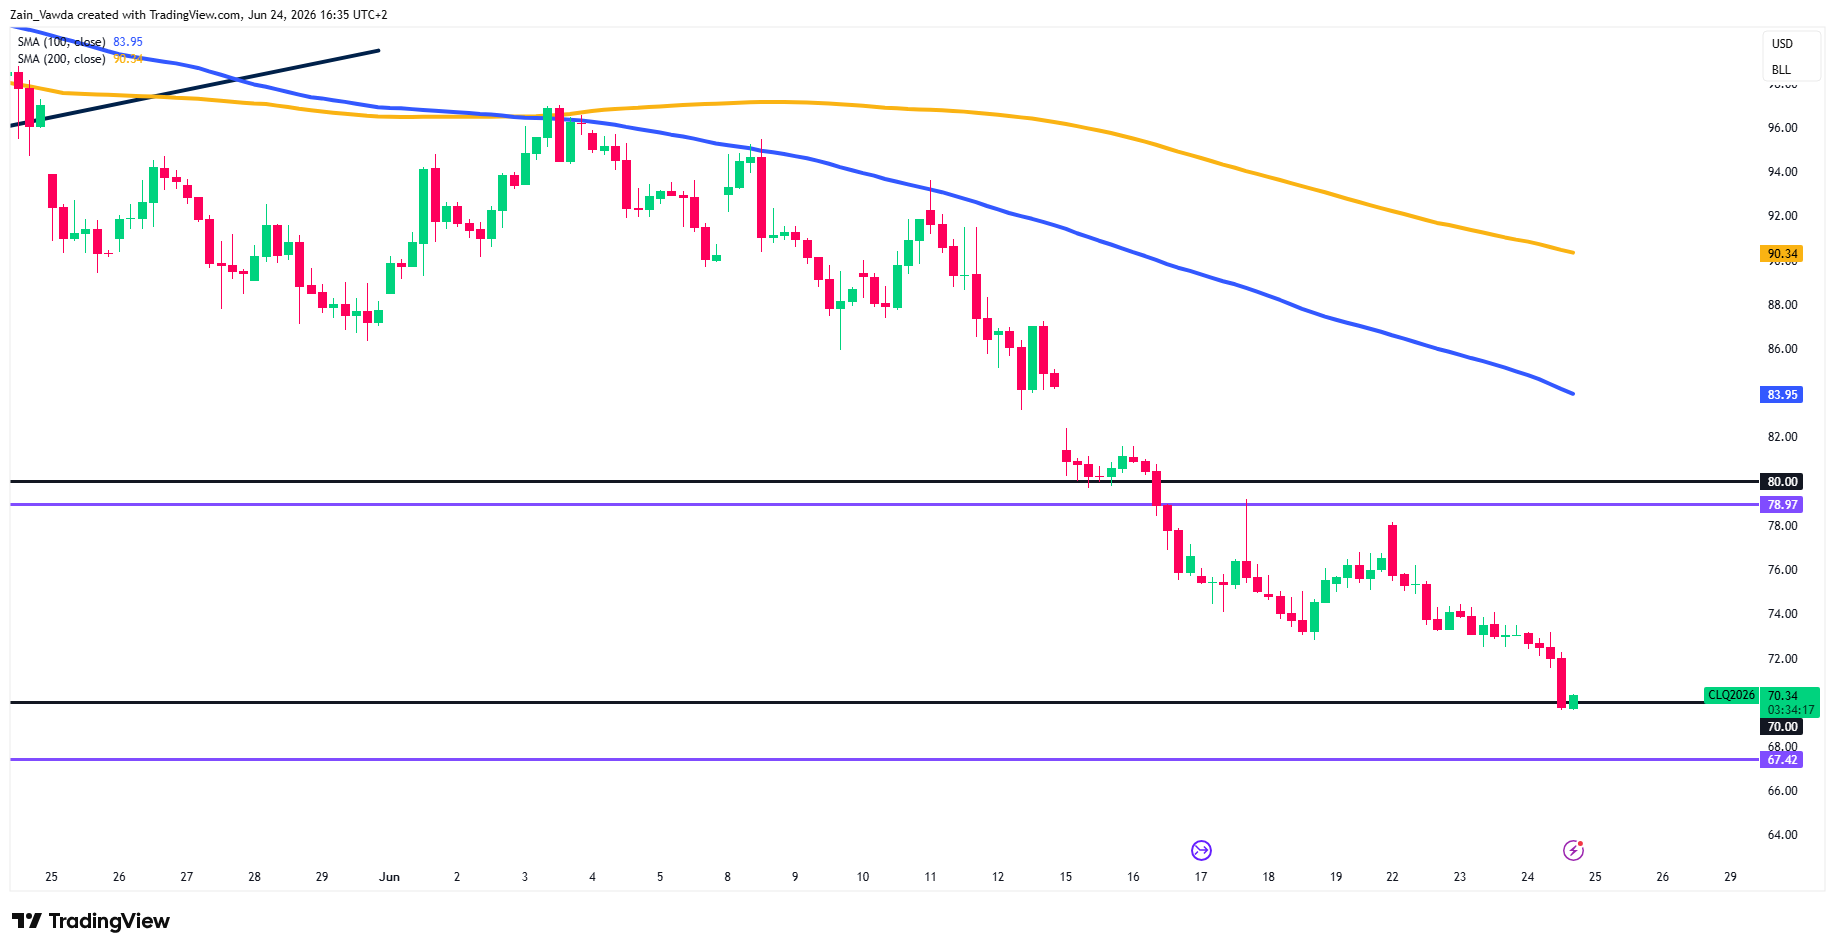
Source: TradingView
For Gold and Silver, the picture is equally painful near-term. Gold futures dropped 3.5% to breach the $4,000/oz handle on Wednesday, silver fell 4.65% to a low of around $58.00/oz, both repricing against a DXY that has no obvious ceiling while hike probability stays elevated.
The structural bull case in gold remains intact long-term, but a live Fed hike cycle is the one macro regime that genuinely tests it. Real yields matter here — if Thursday's PCE print comes in hot and ZN sells off further, gold bears have a green light.
For S&P and Nasdaq traders, higher-for-longer is the enemy of multiple expansion. This week's tech flush — Nasdaq down below 30,000 wasn't purely an AI earnings story. It was rates repricing into richly-valued growth. The two forces are compounding.
The Cross-Asset Read: EUR/USD, USD/JPY
EUR/USD has retreated to approximately 1.143 despite the ECB hiking to 2.25% on June 11. The Fed's rate advantage is simply overwhelming the eurozone's own tightening cycle.
USD/JPY remains the most dangerous pair in the complex: intervention risk from the Ministry of Finance is elevated, and any sharp yen reversal would unwind a significant carry trade that has supported risk assets globally. Watch it closely.
The Catalyst: Thursday's PCE
Everything narrows to Thursday morning. The Fed revised its year-end Personal Consumption Expenditure (PCE) forecast to 3.6% — if May PCE confirms that trajectory, September hike bets move toward certainty. That scenario maps directly onto: DXY extending toward 102+.
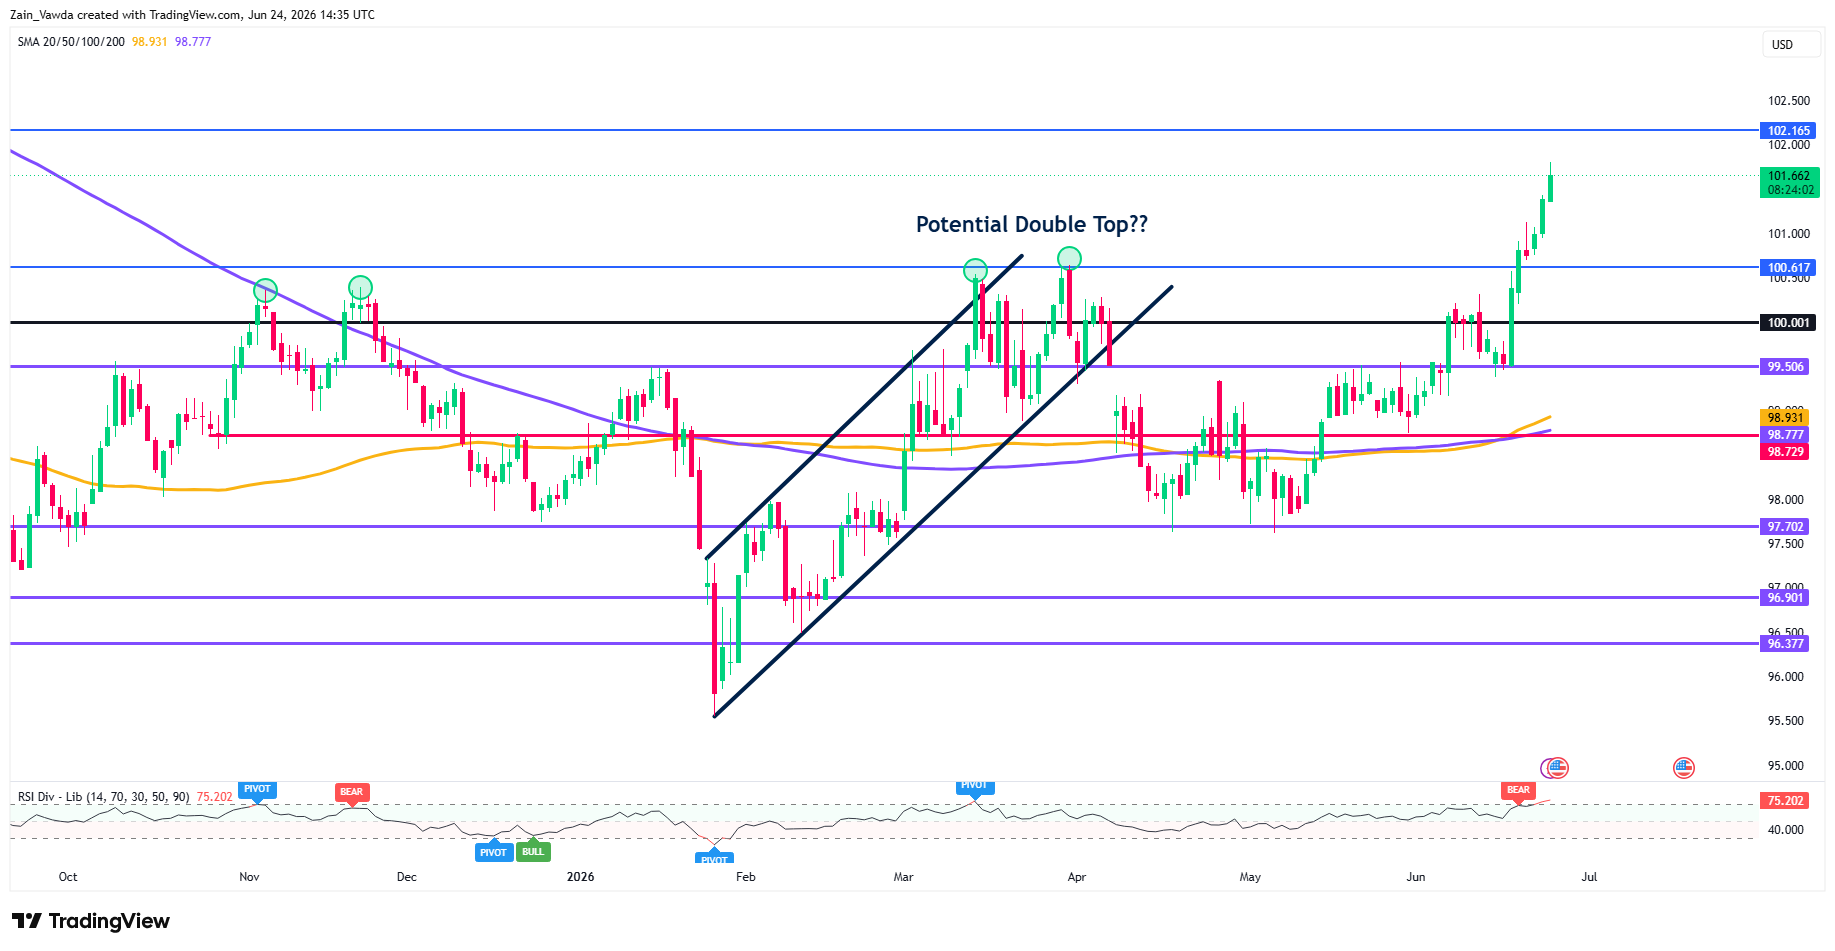
US Dollar Index, Four-Hour Chart, June 24, 2026
Source: TradingView
For the DXY, there is a key multi-month year level which rests just above the 102.00 handle at 102.16.
A break above this level could be crucial and may open the way for a run toward the 105.00 psychological handle.
A rejection here which is possible as the RSI hovers in overbought territory could lead to a retest of support at 100.61 or lower at the psychological 100.00 mark.
A softer PCE print gives bulls a window — but given the energy shock embedded in the CPI data, a genuine undershoot looks unlikely.
The Fed hike trade is repricing every asset class simultaneously. Until Thursday's data changes the calculus, DXY is the tape.


